
For millions of Nigerians, securing a place to live is less about choice and more about timing, luck, and cash flow. Rent is demanded upfront, often for one or two years, in a country where income is largely earned monthly, and house rent has risen by nearly double digits over the last five years.
This disconnect has quietly locked many working Nigerians out of decent housing, especially in a city like Lagos, not because they can’t afford rent, but because they can’t afford to pay everything upfront.
To fill this gap, Ule Homes was born. What started as a group project has evolved into a rent-financing and housing credit startup that aims to revolutionise how Nigerians access housing by converting lump-sum rent into manageable monthly payments, while also quietly building users’ credit histories in the process.
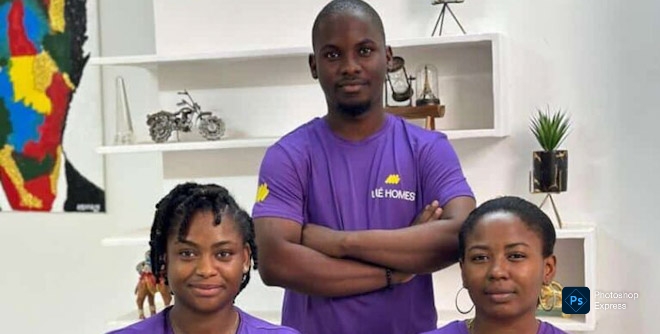
Founded in 2024 by Chisom Okorie, Omolade Akinwumi, and Azeez Abdulyekeen, who met during a postgraduate programme at the Nigerian University of Technology and Management, Ule Homes officially launched in August 2024. In less than a year, the proptech has disbursed over ₦700 million in rent and housing finance to more than 182 paying customers, primarily across Lagos, Abuja, and parts of Ibadan.
“We wanted to make housing easier and more bearable for people,” Omolade Akinwumi, Co-founder and CEO of Ule Homes, says.
The company was selected for the Antlers 2025 programme and had won the Moonshot startup battlefield in October 2025.
The motivation behind the proptech
The motivation behind Ule Homes is personal. None of the founders grew up in Lagos, a city whose rent market operates on entirely different rules from much of Nigeria. Coming from places like Jos and Bauchi, where rent is relatively affordable, Lagos presented a harsh reality: rent increases rapidly, requires lump-sum payments, and leaves even salaried workers scrambling.
“Lagos felt like a new terrain for us. I grew up in Ibadan, Chisom and Azeez grew up in the northern part of Nigeria. Coming from places like that where rent was relatively cheap, it felt like we had to struggle to afford a good house, especially as working professionals,” Akinwumi tells Techpoint Africa.
What made the problem more urgent was timing. Saving for rent in Lagos often meant chasing a moving target, and by the time savings were complete, prices had jumped again. For young professionals and business owners alike, this creates a cycle of stress, delays, and compromised living conditions.
markup on funds provided by its partner financial institutions. A one-time fee is also charged per transaction. Combined, the company earns an average 10.8% margin per customer.
From ₦700 million disbursed, Ule Homes has generated approximately ₦75 million in revenue, translating to roughly ₦5 million per customer cohort plus facilitation income.
“We have financial institutions that back Ule Homes with funding and loans. That has helped sustain us,” Chisom Okorie, Co-founder and COO of Ule Homes, says.
A heavy reliance on external financial partners, exposure to macroeconomic shocks that affect income stability, and interest rate sensitivity in a volatile Nigerian economy pose existential threats to the business. While profitable in the early stages, long-term sustainability will depend on diversification beyond rent financing and deeper automation to reduce operational overhead.
Competitive advantage and what the future holds
Unlike many rent-financing platforms, Ule Homes deliberately integrates credit education. Users can access their credit reports directly on the platform, helping them understand how rent repayment improves long-term access to loans and mortgages. Its property-agnostic financing makes it easy for users to finance any apartment, not just partner-managed listings.
Looking ahead, the company’s roadmap points toward expansion and inclusion. Ule Homes is working towards the launch of a fully automated web app.
The company is also eyeing entry into other African markets, starting with Ghana. Aside from rent financing, Ule Homes is building savings-led products tailored to rent and housing goals.
If successful, this shift could significantly expand Ule Homes’ addressable market, bringing housing finance to traders, artisans, and informal earners typically excluded from formal credit systems.
